How do I avoid wire fraud when buying a home? Never accept wire instructions by email. Call the title company at a number you already had, not one from the email and verbally confirm the account before sending anything.
A couple of years ago I had a deal about a week out from closing. My clients were selling their house and buying another one, and they got an email from the title company asking them to wire the funds for their purchase.
They called me and they were annoyed. Not scared. Annoyed. Because the title company knew perfectly well they would not have that money until their current house closed and here was this email asking for it anyway.
I asked them to forward it to me and not to respond.
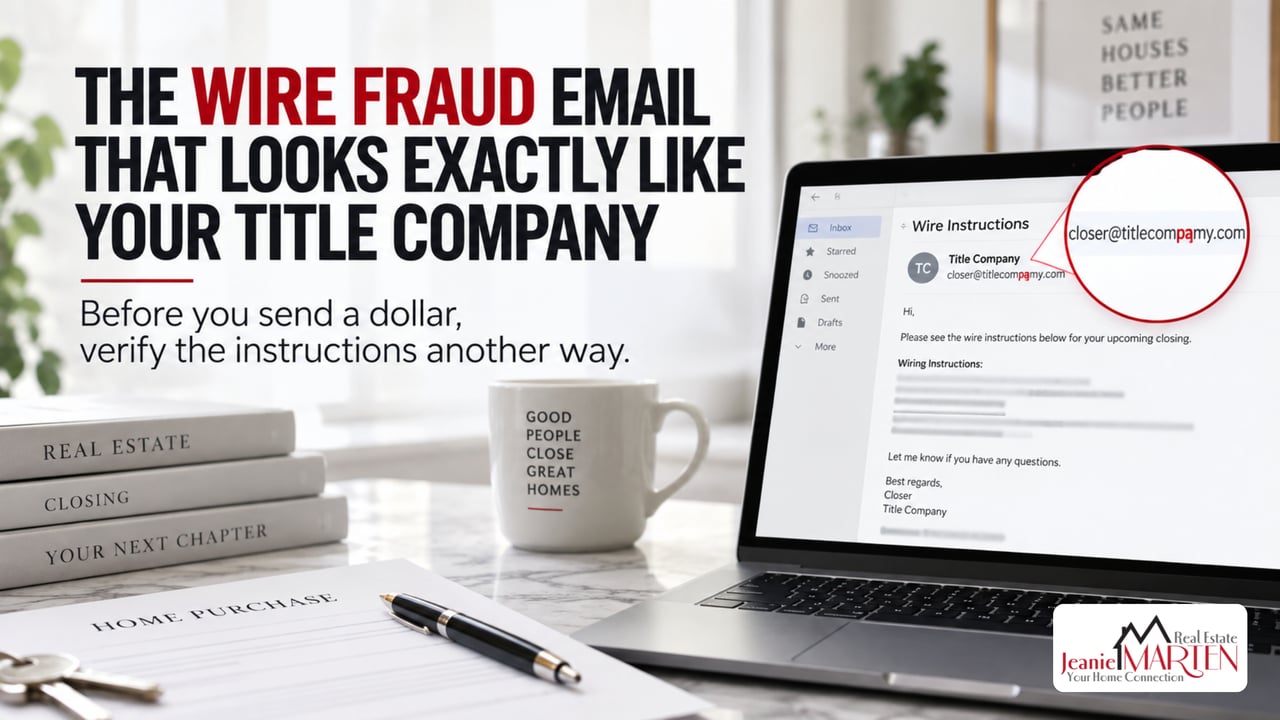
The email address was one letter off from the real closer's. Her signature block had been copied exactly. Logo, phone number, disclaimer, all of it. If you were not looking at the sender's address character by character, there was nothing to see.
Here is what I want you to notice about that story because it is not the lesson most people take from it. My clients were not saved by spotting the fake domain. They never looked at it. They were saved because the request did not make sense for where they were in their own transaction and instead of complying they picked up the phone to complain.
That is the actual defense. Understanding your own deal well enough to know when something is off.
This is the most expensive mistake in residential real estate
The FBI publishes an annual report on internet crime and the numbers are worth sitting with.
In 2025, Americans reported nearly $20.9 billion in losses. Business email compromise, which is the category this attack falls under, accounted for 24,768 complaints and just over $3 billion. The real estate category alone accounted for 12,368 complaints and more than $275 million in losses.
Those are only the reported ones. A lot of people never file, either because they are humiliated or because they do not know where to report it.
And the amounts are catastrophic in a way most fraud is not. This is not a $200 gift card scam. This is your entire down payment, or your entire proceeds from selling a house, gone in a single transfer.
How the fake email actually gets made
Understanding the mechanics helps, because once you see it you cannot unsee it.
They are already watching. Somebody's email has been compromised, or a mailbox somewhere in the transaction is being monitored. It might not be yours. It might be an agent, a lender, an assistant, or someone at the title company. That is how the criminal knows your name, your closing date, your address, and roughly what you owe.
They wait for the right moment. The email showed up a week before closing because that is when wire instructions become believable. Fraud that arrives at the right moment does not feel like fraud. It feels like the next step.
They register a domain that looks correct. One letter changed. An "rn" instead of an "m." A missing letter nobody counts. Your eye reads what it expects to read, especially on a phone, where most email clients show you a display name and hide the actual address entirely.
They copy the signature. In my clients' case the closer's signature block was reproduced exactly. That is not sophisticated. Every email that person has ever sent contains it.
They create urgency. Wire today. Closing is at risk. The lender needs it now. Urgency is the tool that stops people from making the one phone call that would end the whole thing.
Some versions are getting better than this. Voice cloning is real and a call back to a number the criminal supplied can now sound like a person you have spoken with before. Which is exactly why the number matters more than the voice.
Once it is sent, it is usually gone
Wire transfers are not credit card charges. There is no dispute button and no chargeback. The money moves, it gets pulled out or moved onward within hours and your bank has no obligation to make you whole because you authorized the transfer yourself.
Here is the part I most need you to hear: your title insurance does not cover this. Neither does your homeowners policy in most cases.
That surprises people, so let me be precise about why. Title insurance covers defects in the title to your property, things like a forged deed or an undisclosed heir. Wire fraud is not a title defect. It is theft of your money, accomplished by convincing you to send it voluntarily. Because you authorized the transfer after being deceived rather than having funds taken through a system breach, standard policies generally do not respond and the loss sits with the person who sent it.
You can buy an owner's title policy and still lose your entire down payment to this. They protect against completely different things.
What to do in the first hour because the clock is real
If you have already sent it, stop reading and start calling. Speed is nearly the whole game.
- Call your bank immediately and ask them to issue a recall or a SWIFT indemnity on the wire. Use the fraud department not the branch. Do this before anything else.
- Call the title company on a number you know is real, and tell them exactly what happened.
- File at IC3.gov. This is the FBI's Internet Crime Complaint Center and it is what triggers the federal response.
- Call your local FBI field office. Have ready the incident summary, both bank names, both account numbers, the SWIFT number if international, the date and the amount.
- File a police report with your local department.
- Talk to a real estate attorney the same day.
The reason for the urgency is a program called the Financial Fraud Kill Chain. When it is triggered fast enough, the FBI's Recovery Asset Team works with banks to freeze funds before they disappear. In 2025 that team actioned 3,900 incidents, froze $679 million and reported a 58 percent success rate.
Fifty-eight percent is genuinely good odds and they are available only to people who move immediately. The formal kill chain criteria for international wires require the transfer to be $50,000 or more, within the last 72 hours, with a SWIFT recall already initiated. Smaller or domestic wires should still be reported right away because banks can sometimes recall those on their own.
Every hour you spend hoping it was a misunderstanding is an hour the money is moving.
How to make sure it never happens to you
Never trust wire instructions that arrive by email. Not from your title company, not from me, not from your lender. Treat every emailed set of instructions as unverified until you have confirmed it out loud.
Call to verify using a number you already had. Not the number in the email. Not the number in the signature block. The number from the title company's website that you looked up yourself or the one you saved when you first spoke with them. A criminal who can fake an email address can fake a phone number in that same email.
Verify the account number digit by digit, out loud, with a human being. Every digit. This takes ninety seconds and it is the single most effective thing on this page.
Ask your title company up front how they send instructions. Many now use a secure portal and will tell you plainly that they never email wiring details. Ask at the beginning of the transaction not the week of closing.
Be suspicious of any change. Legitimate title companies almost never change wire instructions mid-transaction. An email saying the account has been updated should be treated as fraud until proven otherwise.
Slow down when someone tells you to hurry. Urgency is the weapon. No real closing has ever been lost because a buyer took twenty minutes to make a verification call.
Call after you send to confirm the funds landed. If something went wrong, those few hours matter enormously.
And know your own transaction. This is what saved my clients. They knew what they owed, when they owed it and where the money was coming from. When a request did not fit that picture, they questioned it. If you do not understand your own numbers, ask your agent to walk you through them, because a person who understands their deal is very hard to defraud.
Most of this happens in the window between going under contract and closing, and I walked through what that window actually looks like in What Actually Happens Between Under Contract and Closing Day.
Please forward this to someone
I do not usually ask that. I am asking here.
The people most at risk are first-time buyers who do not yet know what normal looks like and older sellers who are moving a large amount of money for the first time in decades. If you know somebody buying or selling in the next few months, send them this before their closing week, not during it.
Frequently asked questions
Does title insurance cover wire fraud? No. Title insurance covers defects in the title to the property, such as a forged deed or an undisclosed heir. Money you wire to a criminal is theft rather than a title defect, and because you authorized the transfer after being deceived, standard policies generally do not cover the loss.
Can a wire transfer be reversed if I was scammed? Sometimes, but only if you act within hours. Contact your bank's fraud department immediately to request a recall, then file at IC3.gov. The FBI's Recovery Asset Team froze $679 million in 2025 with a 58 percent success rate, and that success depends almost entirely on how fast the victim reports it.
How do I verify wire instructions safely? Call the title company using a phone number you obtained independently, such as from their website or from your earliest correspondence, and never a number contained in the email with the instructions. Confirm the account number digit by digit with a person. Do not rely on email, text, or a callback number the sender provided.
If you found this useful, read these next
- Don't Let a "Roaming Roofer" Turn Into an Expensive Mistake covers the other scam that shows up around North Texas homes, and it works on the same principle of manufactured urgency.
- Who Do You Trust? is about building a vetted list of people before you need them, which is the same defense applied to contractors instead of closings.
If you are closing in Sachse, Wylie, Murphy, Rockwall, or Rowlett and you have any doubt at all about a wire request, call me first. I would far rather look at a legitimate email with you than help you file a police report.
Jeanie Marten Real Estate is a brokerage, not a bank or a law firm. If you believe you have already sent funds to a fraudster, contact your bank's fraud department and file at IC3.gov immediately, then speak with an attorney.
Visit MartenTeam.com or book a consultation.
Jeanie Marten Real Estate 972-414-0719 | MartenTeam.com